- Fixed for life at 4.71% with Nationwide Lifetime Mortgages
- No fees payable to brokers or advisers
- You’re free to make monthly payments if you wish
- Early repayment charges do not apply
- Free valuation included with your application
- A mortgage designed to last throughout your lifetime
To explore whether a Nationwide Lifetime Mortgage is suitable for you, please complete the form below:
Nationwide Lifetime Mortgages Explained in Simple Terms
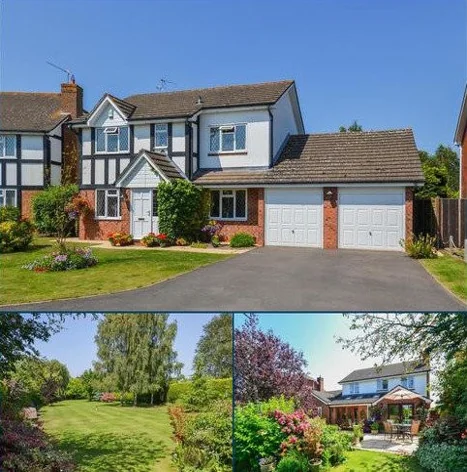
A Nationwide lifetime mortgage is a popular solution for homeowners aged 55 or over who want to unlock their home’s value without selling. It allows you to access a cash lump sum or draw down funds over time, using a mortgage secured against your home. To be eligible, your property usually needs to be worth at least £70,000 and of a suitable construction type.
This form of home finance provides flexibility and choice. Some plans are structured as lump sum mortgages, while others offer drawdown options. You can choose whether to make repayments or release equity without repayments, with the loan repaid when you die or move into long-term care. As with any financial product, it’s essential to understand the fees involved, including legal and arrangement charges, and how your property value affects the amount available.
A lifetime mortgage can also affect your estate and any future inheritance for your children. The Nationwide lifetime mortgage may reduce the value of your estate and could influence your exposure to inheritance tax. These are essential considerations when deciding whether a lifetime mortgage is right for you.
Before starting an application, it’s recommended to speak with an adviser who can guide you through the range of available options and answer all your questions. Many people find it helpful to consider their decision through a series of discussions with family and professionals.
If you’d like personal support or need further clarity, you can request a callback to speak with an expert who can walk you through your options and help you find the right path for your needs and goals.
Can You Get a Lifetime Mortgage with an Existing Mortgage?
Yes, you can take out a lifetime mortgage even if you have an existing mortgage on your home. In fact, one of the most common uses of a Nationwide Lifetime Mortgage is to repay the outstanding balance on a standard residential mortgage.
This approach can help homeowners approaching retirement who want to remove monthly repayments and access additional funds for home improvements or other purposes.
To qualify, you’ll need to meet the provider’s eligibility criteria, which usually include being over 55 and having sufficient equity in your home. The amount you can borrow depends on your home’s value, your age, and the plan’s specific terms.
A regulated lifetime mortgage adviser will assess your situation and provide a personalised recommendation to help you choose a product that suits your goals.
Many plans now offer added flexibility, including no early repayment charges and options for inheritance protection, which allow you to ring-fence a portion of your property’s value for your loved ones.
This is particularly important if you’re concerned about leaving something behind after selling the home or planning for the rest of your financial life.
A lifetime mortgage can also serve as a downsizing alternative, helping you remain in your current home while still accessing the funds you need.
The Financial Conduct Authority regulates plans, and all reputable providers are committed to transparency and consumer protection. Some advisers operate on a no-advice-fee basis, offering you professional guidance at no upfront cost.
Make every decision with care, and review all options with a qualified adviser who understands the intricacies of a Nationwide lifetime mortgage. If you’re unsure where to begin, a trusted adviser can guide you through the available options, making the process straightforward and stress-free.
Loan-to-Value Explained for Nationwide Lifetime Mortgages
When considering a lifetime mortgage plan, understanding loan-to-value (LTV) is key to making informed decisions. LTV refers to the percentage of your property’s value that you can get through a loan secured against your home. The actual percentage available depends on factors such as your age, health, interest rate, and the lender’s specific plans.
Typically, the older you are, the higher your LTV. You can use it to access a tax-free cash lump sum, repay debts, make payments toward home adaptations, or assist a family member. The goal is to select a product offering the right terms and flexibility to meet your needs today and in the future.
To begin, you can use a simple calculator to estimate your potential borrowing, though a personalised amount calculation is always recommended.
During an appointment with a qualified adviser, they will review your personal and financial details to confirm your eligibility. The adviser will also provide tailored information and guide you through available options.
All products should comply with the Equity Release Council’s standards, including safeguards such as the no-negative-equity guarantee. This is especially important when considering the future impact on your estate and your ability to pay for long-term care or leave an inheritance.
A dedicated team will help you through the whole process, from assessing your needs to selecting the most suitable plan. The cash you release could also affect any benefits you currently receive, so it’s essential to understand how your entitlement might change. Speaking to a regulated adviser ensures you’re guided through every step, with your long-term goals and family interests in mind.
What Can I Use the Nationwide Lifetime Mortgage Money For?
Many people exploring a lifetime mortgage want to understand how they can use the money they release. Whether you’re planning your retirement, managing household costs, or helping family, the funds can support a wide range of financial goals. One common reason is to release equity in your home to pay off an existing mortgage, easing monthly commitments and improving peace of mind.
As a homeowner, you can use your borrowing in a way that suits your situation. Your home’s value and your age will influence how much you can access, and a qualified adviser can help you review your options. Products vary across the market, and features vary depending on the product and provider.
Some customers choose to take a single lump sum, while others prefer plans with optional monthly repayments.
In many cases, you can make monthly payments to service the interest and reduce the overall impact on your estate. This process is supported by clear documentation, including a personal illustration that shows how the plan would work over time.
Nationwide Lifetime Mortgages can also supplement income, fund home improvements, or support loved ones. However, you should consider how accessing these funds may affect your means-tested benefits. A qualified adviser will explain how your current and future entitlements may be impacted based on the plan you choose.
Ultimately, a lifetime mortgage offers flexible financial solutions tailored to your goals. With the right advice and planning, it can provide a valuable source of money to help you enjoy greater security and freedom in later life.
Will I Still Own My Home?
Yes, if you take out a lifetime mortgage, you will still own your home. A nationwide lifetime mortgage does not mean giving up ownership. Instead, it is a borrowing option for people aged 55 and over, secured by a legal charge over the property.
This allows the borrower to access funds for a range of purposes, from building a cash reserve to funding a better lifestyle, while remaining in the property for the rest of their lives.
Providers assess each applicant’s circumstances carefully, including health, income, and future goals. Providers must review all applicant circumstances, especially where a partner is involved or the recipient is entitled to state benefits. Releasing equity may affect your entitlement to means-tested support, depending on how much is released and how the funds are used.
A key safeguard is the no-negative-equity guarantee, which ensures that neither you nor your loved ones will ever owe more than the property’s value, regardless of interest rates or how long you remain in the home. This protection is standard on plans offered by providers approved by the Equity Release Council.
Nationwide Building Society Lifetime Mortgage and Loan Summary
Nationwide Building Society is a mutual owned by its members, with a broad portfolio spanning retail savings, lifetime mortgages, investment and insurance services, and commercial and corporate banking. It has historically maintained an offshore presence in the Isle of Man and Ireland and continues to pursue a strong funding strategy through covered bonds.
Regulation is primarily UK-centric under FCA and PRA oversight, with operations outside the UK having been closed in recent years. All contact channels, addresses, phone numbers, and service-specific lines have been provided above, meeting the requirement for comprehensive, structured data.
Nationwide Lifetime mortgage rates in 2026: what to expect
Based on your property value and the amount of your initial lump sum, the current lifetime mortgage rates are about 0.5% higher than the most keenly priced repayment mortgage for someone younger, currently around 4.5%.
If you have a son or a daughter with impaired credit, a regulated equity release adviser may suggest that you can use your property value to borrow more cheaply than they can.
Who is a Nationwide lifetime mortgage likely to suit?
Homeowners planning home improvements.
Property owners 55 and above who have been in their homes a long time might need to release a tax-free cash lump sum for a kitchen replacement, bathroom, or even a home extension or conservatory.
If you borrow money secured against your property and use it to increase the size of your home, this type of value-adding borrowing can improve the value of your home significantly.
Those with an existing mortgage in place
Many people suitable for a lifetime mortgage are property owners aged 55 or over with a mortgage nearing the end of its term who cannot realistically repay it.
Interest-only mortgages were particularly popular around 20 years ago, when many people were advised to use a separate investment plan to repay the capital at the end of the term.
People who have not saved or invested to repay the capital owed, or even people who have built up debts and remortgaged over and over again to unlock cash from their homes
Those aiming to reduce inheritance tax exposure
If you have a son or daughter who has a mortgage or other debts, who is maybe having difficulty with monthly interest costs, not only could you plan for future inheritance tax bills with a lifetime mortgage, but you can often get a fixed interest rate lower than the rates your son or daughter is paying.
Plus, you will not have to make monthly payments. If your son or daughter borrows money for a mortgage or secured loan, they will typically need sufficient income and affordability to reduce the capital balance. With your lump-sum lifetime mortgage, you do not need to borrow the money in the first place.
Are lifetime mortgages a safe option?
Thanks to the Equity Release Council standards, the no-negative-equity guarantee, and the current interest rate, regulation has made lifetime mortgages safe.
Options for repaying a lifetime mortgage early
Yes, depending on the product selected, some have no early-repayment fees. Also, because of how compound interest works, many products will allow you to pay interest to stop the capital owed from increasing over time.